- /
Why the Highest Offer Is Not Always the Best Offer When Selling Your Michigan Home
When multiple offers arrive on a home, most sellers look first at the price. I look at what each offer will actually leave in the seller's pocket, and how likely that number is to hold all the way to closing.
After more than 26 years helping buyers and sellers throughout Northville, Novi, South Lyon, Plymouth, Brighton, Green Oak, and surrounding Metro Detroit communities, I have learned that the biggest number in a transaction is not always the most important one.
Your list price is not your sale price. Your sale price is not your net proceeds. Understanding the difference can change how you price your home, evaluate offers, and plan your next move.
Start With a Realistic Estimate Before You List
Before I meet with a homeowner, I send a seller consultation questionnaire. When someone spends 10 to 15 minutes completing it thoughtfully, I can begin researching their property, their goals, and the comparable homes buyers are considering. Often, that gives us a productive starting point for discussing a pricing range before I even walk through the home. I finalize the pricing recommendation after seeing the property and evaluating the competition.
I also prepare an estimated seller net sheet. That way, we are talking about the amount the homeowner might keep, not just an attractive list price.
My approach to pricing is strategic. The list price is an invitation to the market. I want it positioned to generate the right exposure, bring qualified buyers through the property, and support the strongest terms the market will deliver. Pricing high to leave room to negotiate usually costs sellers leverage.
What Is a Seller Net Sheet?
A seller net sheet estimates the cash you may receive from closing after paying off outstanding loans and accounting for expenses related to the sale. It is an estimate, not a guarantee. The numbers change as the purchase price, closing date, lender payoff, and negotiated terms become known.
For a complete breakdown of the expenses that can appear on a Michigan closing statement, see my Michigan Seller Net Proceeds Guide.
An Illustrative $500,000 Sale
Here is how the calculation works in a hypothetical $500,000 sale.
| Item | Amount |
|---|---|
| Sale price | $500,000 |
| Listing brokerage compensation (example) | -$12,500 |
| Buyer-broker compensation, if agreed (example) | -$12,500 |
| Michigan state and standard county transfer taxes | -$4,300 |
| Illustrative title and settlement expenses | -$1,800 |
| Illustrative property tax adjustment and other charges | -$1,200 |
| Illustrative mortgage payoff | -$275,000 |
| Estimated cash to seller | $192,700 |
Illustration only. All brokerage compensation is negotiable. Actual proceeds depend on the agreed terms, mortgage payoff, taxes, title and settlement fees, concessions, and other charges. This example excludes additional liens and does not calculate taxable gain.
The Mortgage Balance on Your Screen May Not Be Your Payoff
One detail that surprises homeowners is that the balance displayed in their mortgage app may not be the amount required to pay off the loan on closing day. A payoff statement may include interest through the payoff date and other applicable charges. If there are additional loans or liens, those also need to be addressed.
That is why I ask sellers to think beyond the number on their most recent statement. We use estimates when planning, and the closing team obtains current payoff information when the transaction progresses. The Consumer Financial Protection Bureau explains the difference between a loan balance and a payoff amount.
Michigan Selling Costs That Deserve Attention
Most homeowners know there will be expenses associated with selling. My job is to make those costs understandable before they become part of a closing statement.
Michigan transfer taxes
For a typical nonexempt sale in the Metro Detroit counties I serve, Michigan's state real estate transfer tax is $3.75 per $500 of value, or 0.75%, and the standard county real estate transfer tax is $0.55 per $500, or 0.11%. Together, that is about $4,300 on a $500,000 sale. Exemptions and unusual transactions can change the amount. You can review the Michigan Department of Treasury state transfer tax guidance for details on the state tax.
Title, settlement, and property tax adjustments
Title insurance, settlement charges, and property tax adjustments vary with the property and the closing arrangement. No flat percentage fits every seller. I prefer to have actual figures prepared for the particular transaction rather than rely on a blanket percentage.
Condominium and association charges
Condo owners may encounter status letters, transfer or administrative fees, and other association-related charges. In transactions I have handled, some of these costs have ranged from a few hundred dollars to around $1,000. They are easy to overlook, which is why I bring them into the conversation early and confirm the actual amount with the association or management company.
Real Estate Commissions Are Negotiable, and the Details Matter
There has been understandable confusion about real estate commissions since industry practice changes took effect in August 2024. Here is what I explain to sellers: compensation is negotiable, and any payment to a buyer's broker should be evaluated as part of the overall transaction.
Offers of broker compensation are no longer permitted on covered MLS platforms. Compensation can still be discussed through permitted channels outside the MLS.
A buyer may request seller-paid buyer-broker compensation in an offer. That request is negotiable. I review it with the seller alongside price, concessions, financing, and every other offer term.
In some situations, I offer a graduated commission arrangement to align my compensation with the seller's result. We can negotiate different listing-side rates at agreed sale-price thresholds. The terms are documented in writing, and no flat percentage fits every seller.
For an overview of the nationwide changes, see the National Association of REALTORS® settlement resources.
What I Compare When Multiple Offers Arrive
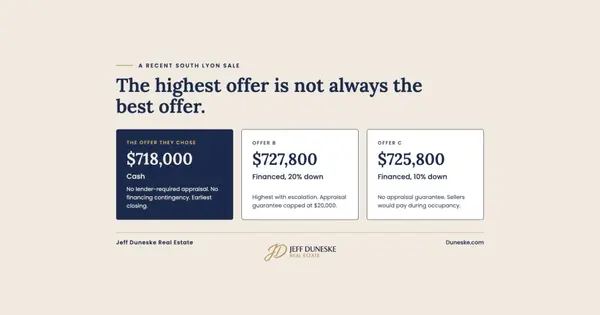
When multiple offers arrive, I prepare a side-by-side comparison so sellers can see more than the purchase price. The strongest offer balances net proceeds, contract terms, and the likelihood of closing.
Here are some of the details I pay close attention to:
- Financing and down payment: Is the buyer paying cash or financing? What do the lender documentation and financing terms tell us?
- Appraisal protection: Is there a meaningful appraisal guarantee or waiver, and can the buyer support the agreed terms if the appraisal comes in low?
- Inspection contingency: How quickly will inspections happen, and what kinds of repair requests does the buyer retain the right to make?
- Earnest money: Is the deposit appropriate for the transaction, and what does the contract say about when it may be retained or returned?
- Buyer-broker compensation and concessions: What is the actual seller-paid amount requested, if any?
- Closing and occupancy: Does the timeline fit the seller's move, and what is the cost or value of any post-closing occupancy agreement?
For example, an offer that waives certain small repair requests can reduce the chance of a series of negotiations after inspection. But the precise contract language matters. A repair threshold is not automatically a waiver of every inspection right or a guarantee that the buyer cannot raise another issue.
How Appraisal Protection Helped Protect a $1.2 Million Offer
At a Lyon Township home in 2026, we listed at $1,095,000, received five offers, and negotiated an original purchase price of $1,200,000. The appraisal came back at $1,080,000, creating a $120,000 gap between the contract price and appraised value.
Rather than reducing the price all the way to the appraisal, we negotiated an amended purchase price of $1,185,000. The buyer agreed to pay $105,000 above the appraised value. The sellers agreed to a $15,000 reduction from the original contract price.
That put the amended price $90,000 above asking. This is why I study appraisal terms and the buyer's financial capacity before recommending an offer. A strong headline price matters, but the ability to support that price matters just as much.
How Occupancy Terms Can Change the Financial Outcome
Another recent sale drew six offers and ultimately produced a price $65,100 above asking. The winning offer also included an appraisal waiver and a pass/fail inspection arrangement. Just as important for the sellers' move, I negotiated 70 days of rent-free post-closing occupancy.
Post-closing occupancy often carries a daily charge based on the buyer's mortgage payment, taxes, and insurance. If that payment were $5,000 per month and the charge were calculated at one-thirtieth per day, 70 days would cost approximately $11,667. We negotiated no occupancy rent, allowing the sellers to avoid a significant potential expense. This is why I compare every major offer term, not just the selling price.
Selling and Buying at the Same Time? Talk to Your Lender Early
For homeowners planning to purchase another property, I encourage an early conversation with a trusted lender. The most useful question is whether you can qualify for your next home without first selling the current one or receiving its net proceeds.
If you can, you may have more flexibility around showings, closing dates, and moving logistics. If you need the sale proceeds for a down payment, we can coordinate timing and explore options with your lender. In some circumstances, a home equity line of credit may be considered, but qualification, repayment, fees, and the ability to carry both obligations need careful evaluation. The lender needs to evaluate the costs and risks first.
Does Net Proceeds Mean the Same Thing as Profit or Taxable Gain?
No. The cash you receive at closing is not necessarily your economic profit or the amount of taxable gain. Your original purchase price, qualifying improvements, selling expenses, tax basis, prior exclusions, rental use, and other factors can affect the tax calculation.
For qualifying sales of a primary residence, federal tax law may allow an exclusion of up to $250,000 of gain, or up to $500,000 for eligible married couples filing jointly. The requirements are specific, so I recommend discussing your situation with a qualified tax advisor. The IRS explains the home sale exclusion here.
Frequently Asked Questions
Do I have to pay the buyer's agent when I sell?
Not automatically. Buyer-broker compensation is negotiable. Whether a seller pays any amount depends on the agreements and negotiations involved in the transaction. I review those terms with sellers before they make a decision.
What happens if the appraisal comes in lower than the contract price?
It depends on the contract. The buyer may cover some or all of the gap, the parties may renegotiate, or the buyer may be able to cancel. Appraisal protection negotiated in the original offer can make a substantial difference.
Why is my mortgage payoff higher than the balance I see online?
A payoff quote can include interest through the payoff date and other applicable charges. A displayed principal balance does not necessarily show the amount needed to satisfy the entire loan on a specific day.
Can a lower offer be better than a higher offer?
Yes. Financing, appraisal protection, inspection provisions, concessions, closing certainty, and occupancy can materially affect the seller's financial outcome and risk. Comparing complete terms is more useful than looking at price alone.
What is post-closing occupancy worth to a seller?
It depends on the length of occupancy, the payment arrangement, ongoing carrying costs, the cost of temporary housing, and the seller's next move. I evaluate it as a financial term, not merely a convenience.
Before You Decide to Sell, Know Your Numbers
I do not believe homeowners should commit to selling before they understand the likely financial outcome. My seller consultations begin with your goals, the details of your home, a market analysis, and an estimated net sheet. From there, we can discuss pricing, timing, preparation, and the contract terms that matter most to you.
If you are considering selling in Northville, Novi, South Lyon, Plymouth, Brighton, Green Oak, or a surrounding Metro Detroit community, I would be happy to help you understand your options.
Explore my Seller Net Proceeds Guide or schedule a conversation. You can also call or text me at (248) 939-9393.
No pressure. Just clarity.
Jeff Duneske, Associate Broker | Jeff Duneske Real Estate | Keller Williams Advantage | Serving Metro Detroit since 2000
Categories
- All Blogs (195)
- Best Agent For… Blog Series - Northville, Novi, South Lyon & Metro Detroit (41)
- Brighton Real Estate Market Updates (3)
- Buyers (23)
- Community & Local Events (2)
- Divorce Real Estate (11)
- Estate Planning & Strategy (7)
- Golf Course & Luxury Living (6)
- Green Oak Real Estate Market Updates (2)
- Homeowners (Maintenance & Equity) (2)
- Investors (1)
- Market Conditions (13)
- Metro Detroit Real Estate Updates (35)
- Mortgage & Financing (2)
- New Construction (3)
- Northville Real Estate Market Updates (14)
- Novi Real Estate Market Updates (17)
- Pricing & Home Values (7)
- Relocation & Moving (7)
- Rightsizing & Senior Moves (10)
- Seller Success Stories (14)
- Sellers (67)
- South Lyon Real Estate Market Updates (18)
- Tips, Guides & How-To (13)
Recent Posts
GET MORE INFORMATION