- /
First-Time Homebuyer Guidance | Metro Detroit
Your first homedeserves a thoughtful plan.
Buying your first home is exciting. It can also bring a lot of questions about financing, neighborhoods, inspections, negotiations, and what happens next. You do not need to have all the answers before we talk. My job is to help you understand your options and make decisions with confidence.
I am Jeff Duneske, an Associate Broker with Jeff Duneske Real Estate at Keller Williams Advantage. Since March 2000, I have helped buyers and sellers throughout Northville, Novi, South Lyon, Brighton, Green Oak Township, Plymouth and nearby Metro Detroit communities.
Start Here
You do not need to be ready to buy to start asking questions.
Some first-time buyers are ready to tour next week. Others are six months or a year away. Both are good times to start a conversation. We can talk through the budget, timing, financing, and communities that fit your life, without any pressure to make a move before you are ready.
Understand your numbers
Learn how down payments, closing costs, property taxes, insurance, and future maintenance fit into your actual monthly budget.
Choose the right location
Compare the neighborhoods, commutes, home styles, and long-term tradeoffs that matter to you, not just the photos in a listing.
Know what you are agreeing to
Get clear explanations of offer terms, inspection choices, appraisals, financing deadlines, and closing costs before you commit.
Financial Preparation
What does buying your first home actually cost?
The down payment is only one part of the financial picture. A lender can help you understand loan options and your estimated monthly payment. I help you think through how those numbers relate to the homes and communities you are considering.
Down payment
You do not automatically need 20% down. Depending on the loan and your eligibility, some programs allow smaller down payments. Your lender can compare the cost and tradeoffs of each option.
Closing costs and prepaid expenses
Plan for lender and title-related charges, prepaid insurance, tax escrows, and other expenses. Ask your lender for a personalized Loan Estimate rather than relying on a generic percentage.
Monthly ownership costs
Look beyond principal and interest. Property taxes, homeowners insurance, mortgage insurance when applicable, HOA dues, utilities, and a maintenance reserve affect affordability.
Cash to keep after closing
Moving, furnishings, unexpected repairs, and normal life do not stop when you receive the keys. It is worth discussing how much savings you want to preserve.
Questions to ask your lender
- What purchase price and monthly payment fit my budget?
- Which loan types should I compare?
- How much cash will I need to close?
- Will mortgage insurance apply?
- Do I qualify for any assistance programs?
- What happens if rates or property taxes change?
Mortgage program details, eligibility, and rates can change. Confirm current terms with a licensed lender.
The Roadmap
From your first conversation to getting the keys.
Every transaction is a little different, but this is the process I help first-time buyers work through.
Talk through your goals
We discuss timing, preferred communities, lifestyle, must-haves, and the questions you want answered before looking at homes.
Get financing clarity
Meet with a lender for preapproval, compare loan options, and establish a budget that feels comfortable, not just one you qualify for.
Search with local context
Tour thoughtfully and evaluate condition, pricing history, location, future resale, and property-specific tradeoffs.
Make a strategic offer
Review comparable sales, competition, contingencies, possession, financing, appraisal concerns, and potential concessions.
Inspect and evaluate
Understand inspection findings, discuss concerns with qualified professionals, and decide whether to negotiate, proceed, or exercise available contract options.
Prepare for closing
Work through appraisal, lender conditions, title, final walk-through, closing documents, and the transition into your new home.
Representation Matters
A strong offer is about more than the price.
Buying a home is not simply about winning a negotiation. It is about understanding what you are purchasing, how the terms affect you, and where risk may be hiding.
Pricing and negotiation
We review recent comparable sales, the home's condition, market response, and seller priorities. Depending on the situation, negotiations might include price, concessions, repairs, closing timing, or other terms. None is guaranteed.
Inspections and due diligence
An inspection may uncover normal upkeep or larger issues involving structure, systems, moisture, safety, or deferred maintenance. I help organize the conversation while licensed inspectors and specialists evaluate technical concerns.
Appraisal and financing risk
What if the property appraises below the agreed price? We discuss this possibility before you offer, including how your contract addresses a shortfall and what your financial exposure could be.
Buyer agreements and compensation
Before touring homes together, we will review a written buyer representation agreement outlining services, duration, and compensation. Fees are negotiable and not set by law. Depending on the transaction, compensation may be paid by the buyer, seller, or another permitted arrangement consistent with the agreement.
Considering a New Build?
Understand representation before touring model homes.
Builder sales teams represent the builder. If you are considering a newly built home, speak with your buyer's agent before your first visit and ask about the builder's registration policies, contract, construction deadlines, inspections, and warranty details. Registration policies can affect whether a builder will work with your agent or offer compensation.
Actual Client Experiences
First homes. Different journeys. Meaningful milestones.
No two first-time buyers start from the same place. Some have a tight deadline. Others wait years for the right timing. These are a few people I have had the privilege to guide through that first purchase.
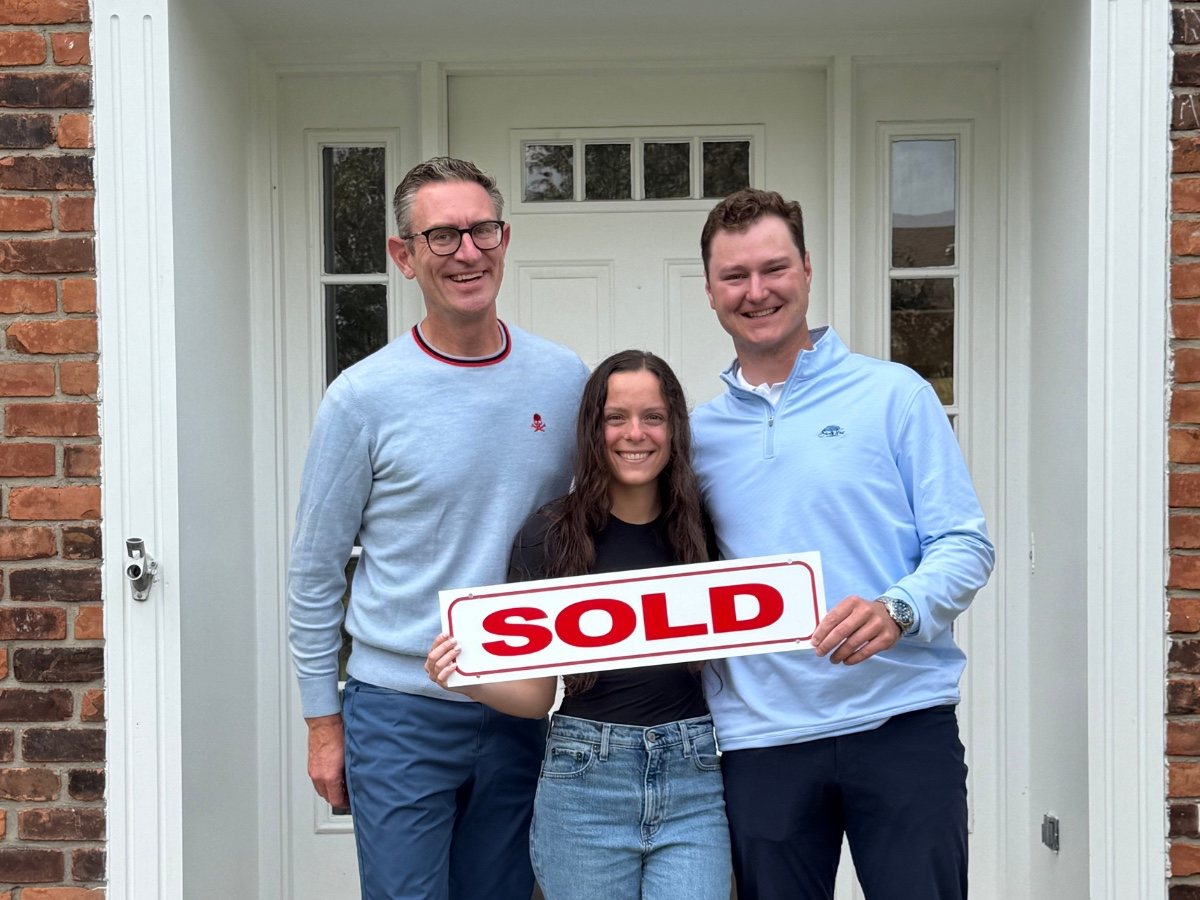
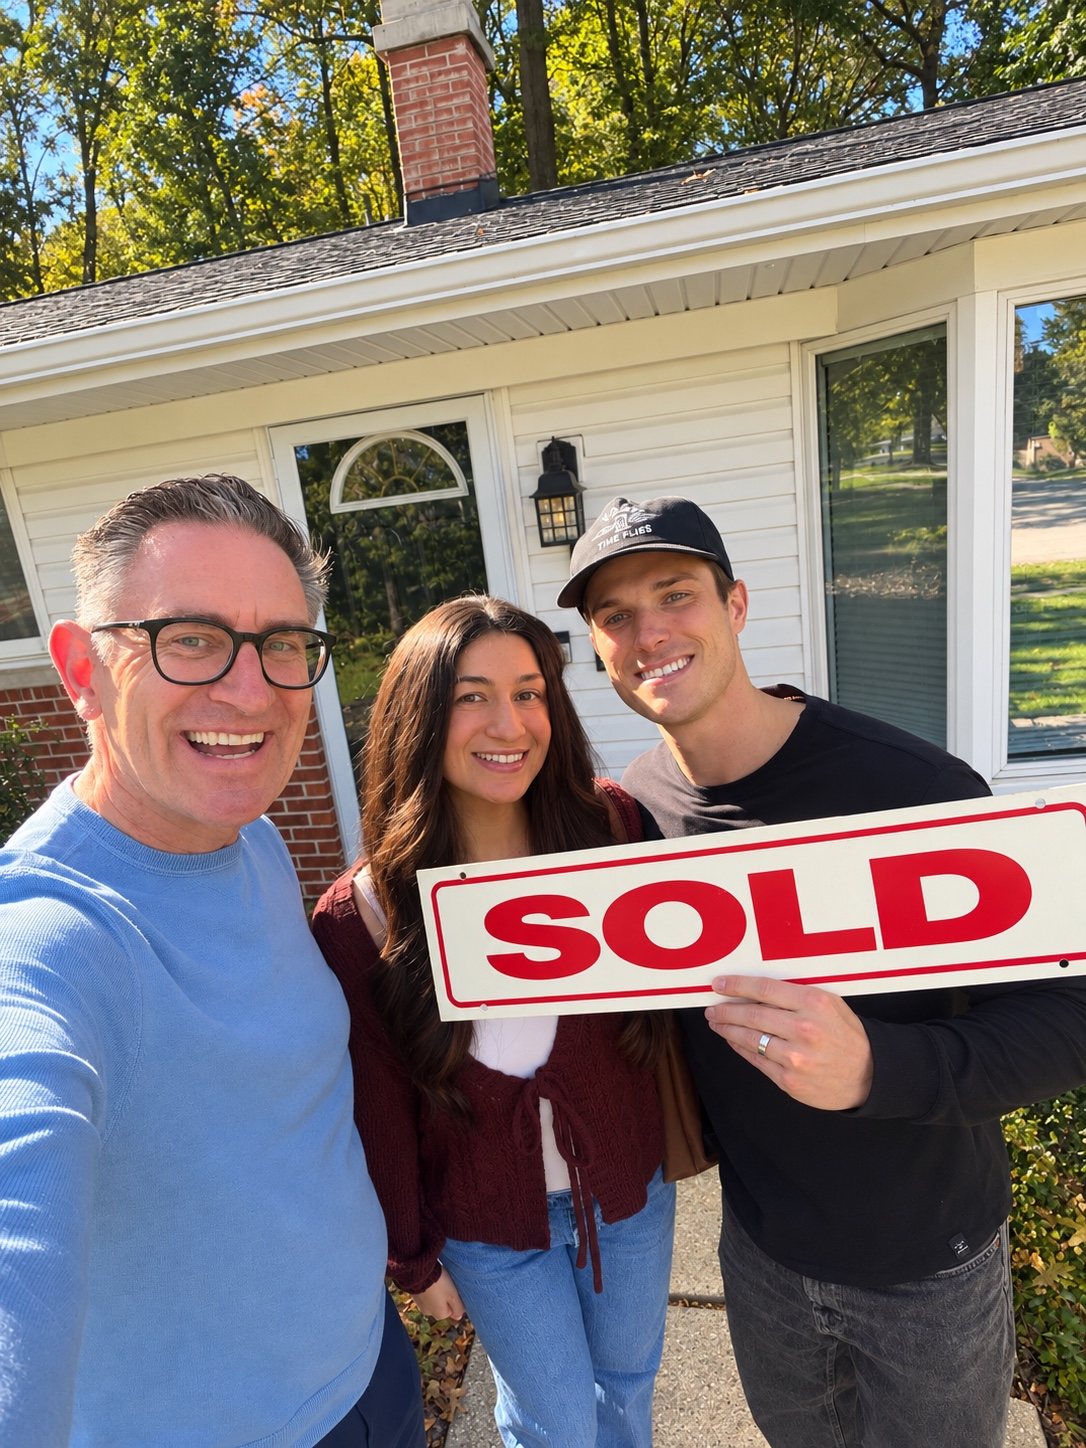
Plymouth, Michigan
Matt & Gabby
First-time buyers with plenty of questions. Clear explanations, patience, and responsiveness helped make the process manageable.
“As first-time homebuyers, we had a million questions but Jeff was a true guide throughout the entire journey.”
Gabby, five-star Google review
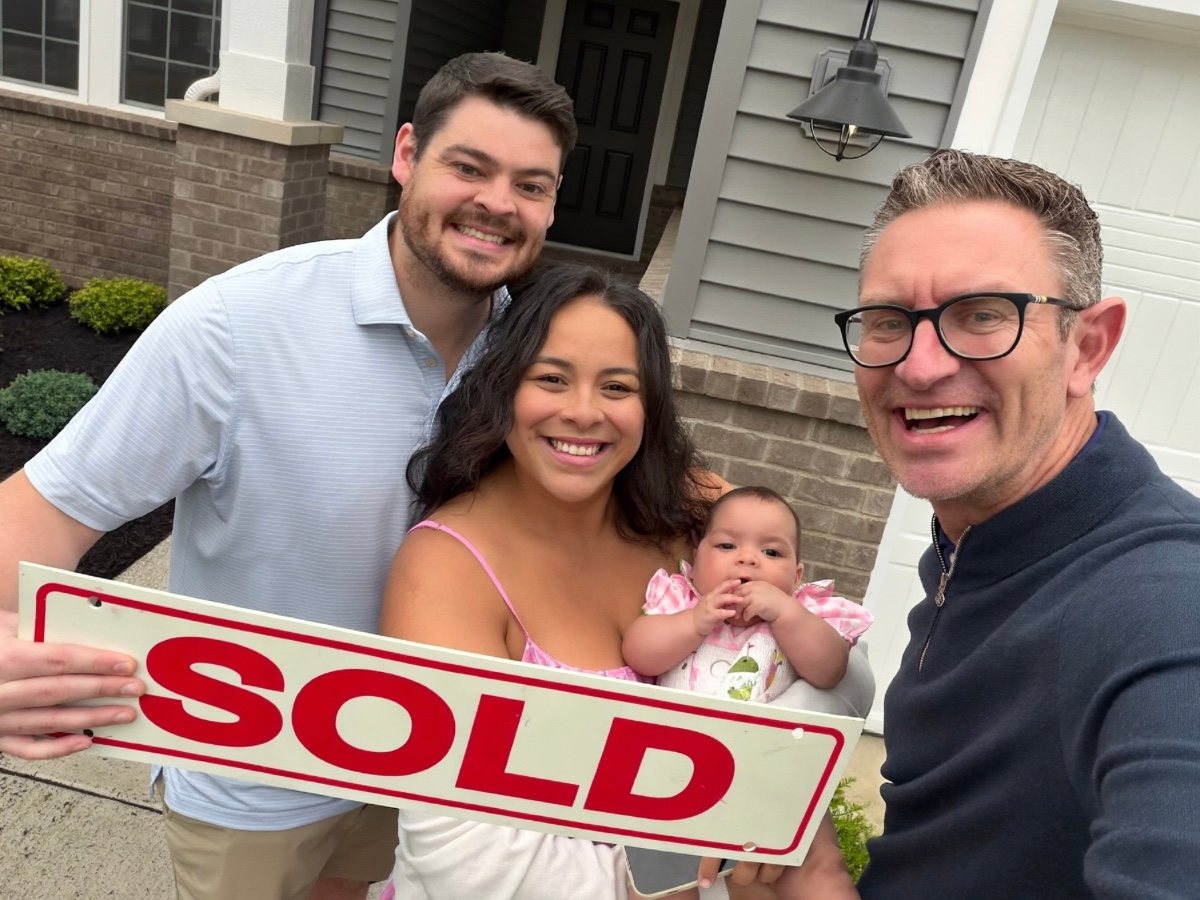
Livonia, Michigan
Matt & Brianna
Newly married and working with a tight rate-lock timeline, they found their first home and got under contract in time.
“I reached out to Jeff when we were looking to purchase a new home on a tight time frame. Jeff exceeded my expectations and we closed on a home we love. Great communication throughout the whole process. Would recommend Jeff to anyone looking to purchase a home.”
Matt, five-star Google review
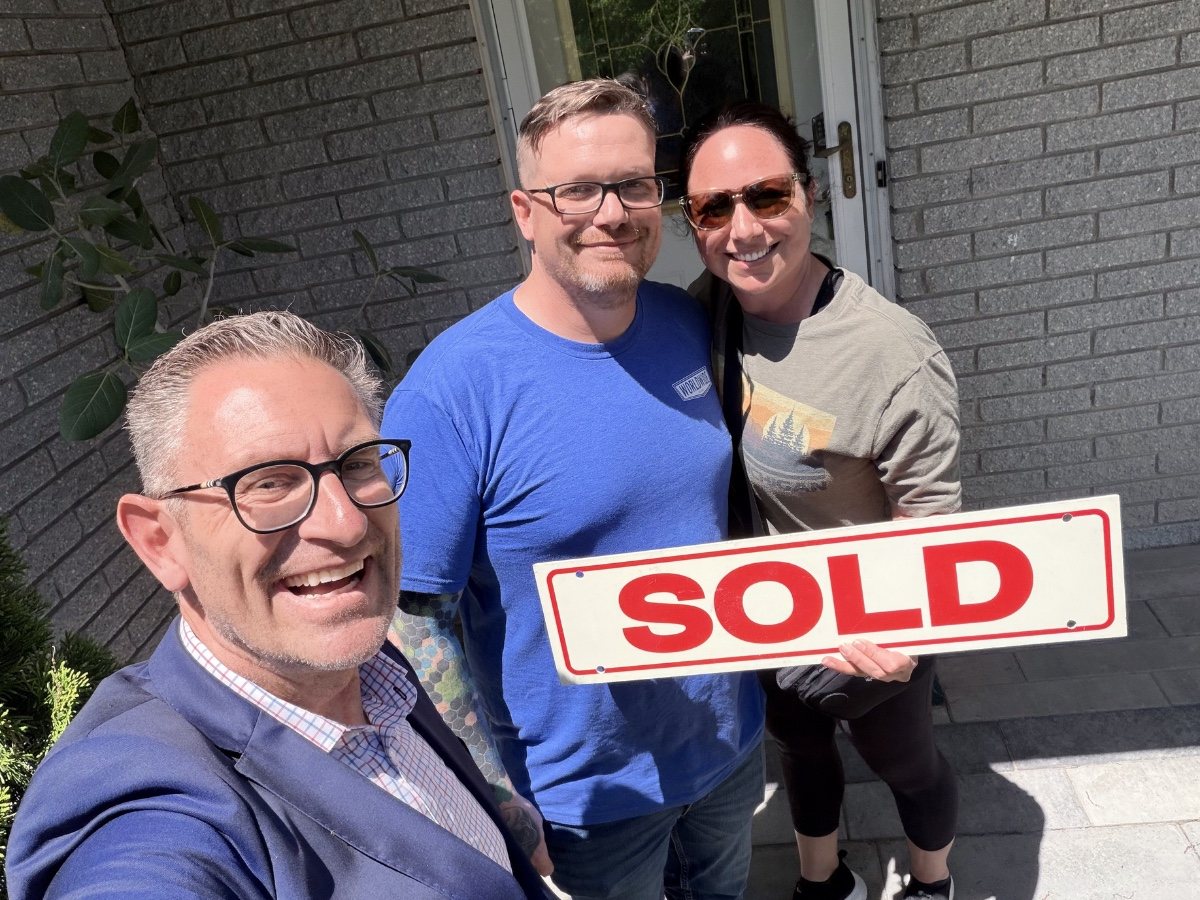
New Hudson, Michigan
John & Claudia
John and I first discussed buying a home in 2018, but his career took him out of Michigan and his plans changed. Eight years later, he returned with Claudia and their young daughter, ready to purchase their first home. We planned their search around the move and explored South Lyon, New Hudson, Lyon Township, and Brighton. After comparing resale homes with new construction, they chose a new Pulte home at Aspen Ridge in New Hudson.
The timing was right for their family, and being able to help another generation of a family I have known for years made the closing especially meaningful.
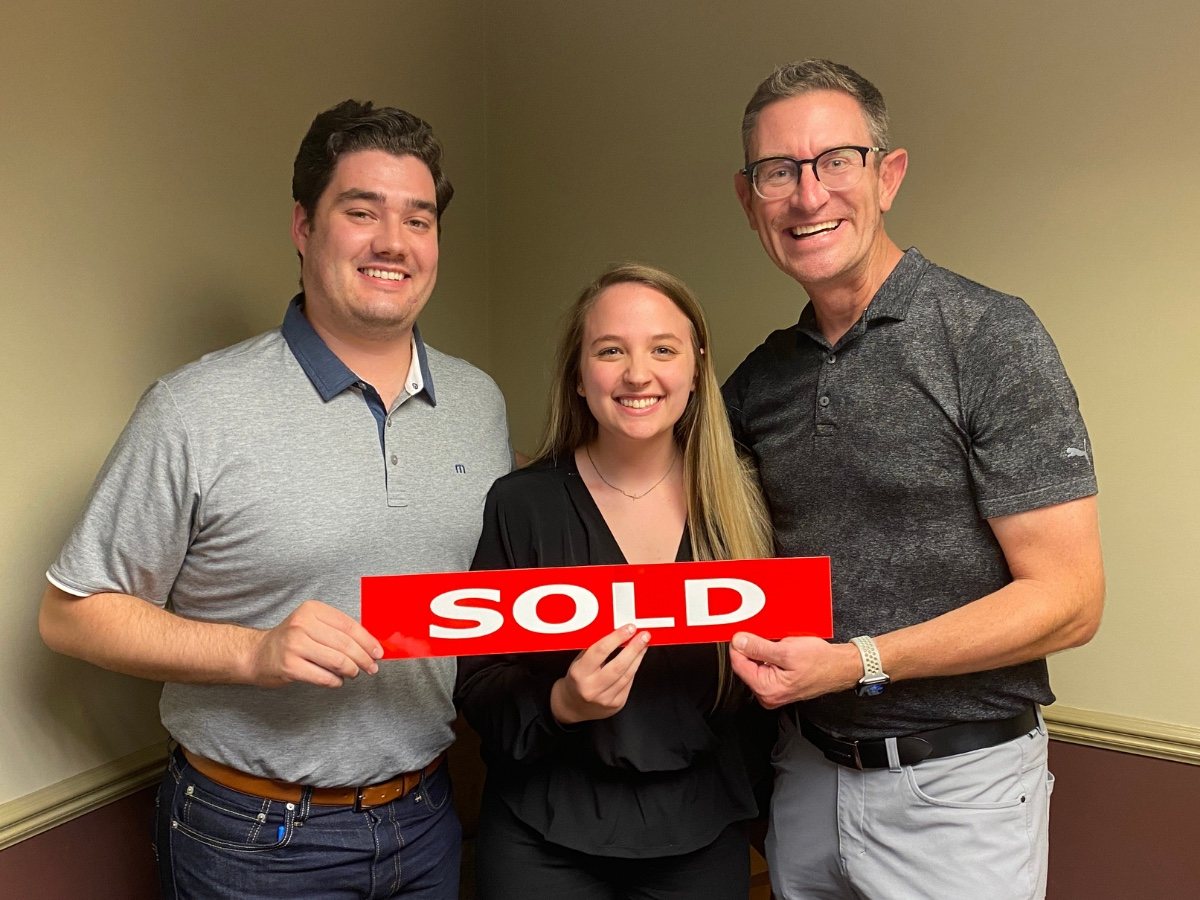
Wixom, Michigan
Gina & James
After helping Gina find a rental years earlier, Jeff helped the couple prepare, navigate a competitive offer, and buy their first home together.
“He explained what the process would be like before we even started looking so we knew what to expect.”
Gina & James, five-star Google review
Livonia, Michigan
Joe & Madison
Their first purchase involved several competing offers. Careful offer strategy and communication helped them secure the home.
“Jeff took the time to walk us through the entire process from beginning to end.”
Madison, five-star Google review
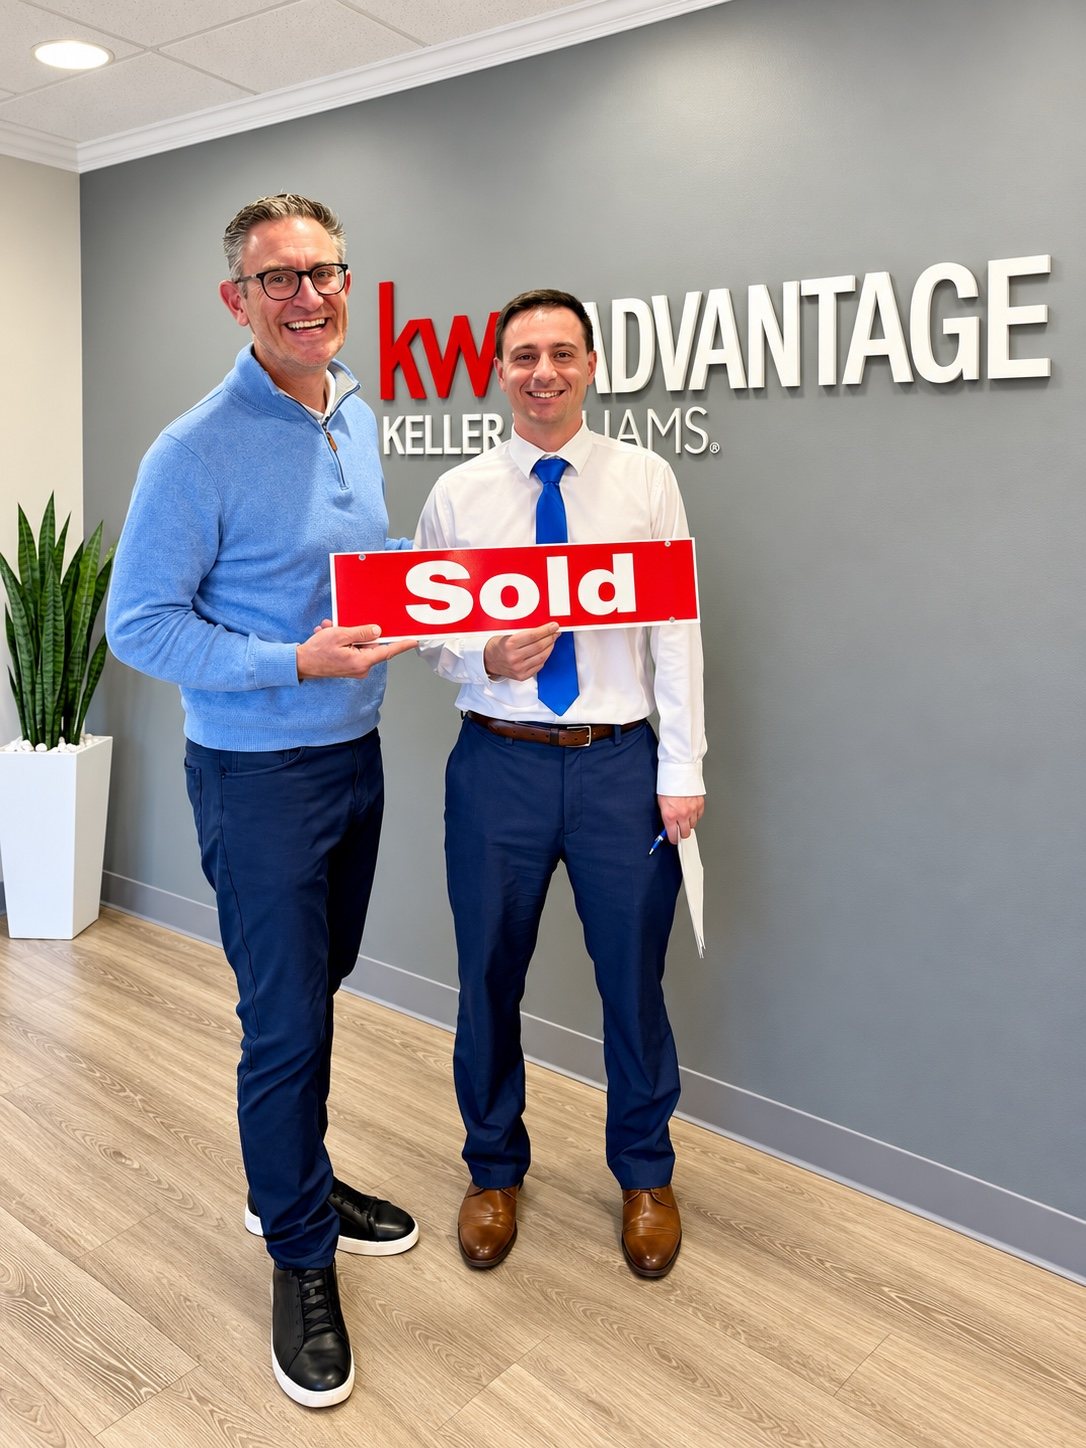
Farmington Hills, Michigan
Daniel
After reconnecting through club volleyball, Daniel began planning for his first purchase as his lease end approached. Through the negotiation process, he secured a purchase price below the original asking price, a seller credit, and a new boiler.
“Jeff is great to have on your side. He is super knowledgeable and will guide you every step of the way.”
Daniel, five-star Google review
Common Questions
Questions first-time buyers ask me.
Do I need 20% down to buy my first home?
No. Different mortgage programs have different down payment requirements. A lender can explain which options you qualify for and how the down payment affects your monthly cost, mortgage insurance, and cash reserves.
Should I talk with an agent or lender first?
Either conversation can be a useful starting point. We can discuss your goals and timing early, while a lender helps you understand what financing may be available and what monthly payment fits your budget.
How far in advance should I start planning?
Even six to twelve months before your intended move can be helpful, especially if you are working on credit, saving money, or deciding between communities. There is no obligation to begin touring right away.
Can I ask a seller to help with closing costs?
Sometimes. Seller concessions are negotiated and depend on the seller, the market, your loan type, and lender limits. We can discuss whether requesting concessions makes sense for a particular property.
Do I need an inspection on a newer home?
An independent inspection is worth considering even for a newer home. Age alone does not eliminate the possibility of defects or incomplete work. Your inspection decisions and contractual rights should be understood before you make an offer.
Will my property taxes be the same as the seller's?
Not necessarily. In Michigan, the taxable value can change after ownership transfers. Before buying, obtain an estimate based on the property's location and your circumstances rather than relying on the current owner's tax amount.
Who pays the real estate agent commission when I buy a home?
Real estate commissions are fully negotiable and are not set by law. Before touring homes together, we will discuss my services and compensation in a written buyer representation agreement. Depending on the purchase, the seller or listing brokerage may agree to pay some or all of that compensation, or the buyer may be responsible for an amount under the agreement. We can also discuss requesting seller-paid compensation as part of an offer. In addition, Keller Williams Advantage charges buyers a separate brokerage transaction fee at closing. I will explain that fee, the compensation arrangements, and any potential out-of-pocket responsibility before you sign the buyer agreement, so you can make an informed decision.
Do I have to sign an agreement before viewing homes with you?
Yes, before we tour homes together, we review a written buyer agreement explaining the services, relationship terms, and negotiated compensation. You are welcome to ask questions or discuss your plans before signing a touring agreement.
Which Metro Detroit communities do you serve?
I work with first-time buyers in Northville, Novi, Farmington Hills, South Lyon, Lyon Township, New Hudson, Plymouth, Livonia, Brighton, Green Oak, Wixom, and other nearby communities. We can compare neighborhoods based on your budget, commute, home style, and priorities.
Start A Conversation
You do not have to figure this out alone.
Whether you are hoping to buy in the next few months or you are just beginning to explore the idea, I am happy to talk through your questions and help you make a plan that fits.
Already scheduled a buyer consultation? Complete the Buyer Consultation Questionnaire before we meet. It generally takes 10–15 minutes and helps me prepare for our conversation.
Jeff Duneske | Associate Broker, Keller Williams Advantage
Let's Talk About Your First Home
Buying your first home starts with a conversation, not a commitment.
Whether you are ready to begin looking or just exploring your options, I am happy to answer your questions and help you plan your next steps.
No pressure, just straightforward guidance.